Yes, with a written agreement put in place before closing. The standard contract runs the other way by default: paragraph 6(a) of the Florida Realtors and Florida Bar AS IS contract has the seller delivering occupancy and possession at closing, free of tenants and occupants, with the keys handed over and personal items gone. Staying past that moment is an added term, and the contract names the rider for it. Two constraints outside the contract decide whether the arrangement works: the occupancy covenant in your buyer’s mortgage, and the law that governs someone living in a home another person now owns.
What the standard contract has you handing over
The form behind most Florida resales is the Florida Realtors and Florida Bar AS IS Residential Contract for Sale and Purchase, ASIS-7x, Rev. 12/26. Paragraph 6(a) reads: “Unless Paragraph 6(b) is checked, Seller shall, at Closing, deliver occupancy and possession of the Property to Buyer free of tenants, occupants and future tenancies.”
The same paragraph pins more to that one moment. At closing the seller “shall have removed all personal items and trash from the Property and shall deliver all keys, garage door openers, access devices and codes, as applicable, to Buyer.” A seller still sleeping in the house, with furniture in the rooms and a garage remote in a pocket, has not performed paragraph 6(a), whatever the closing agent managed to disburse that afternoon.
Paragraph 6(b) is the box that changes the default, and it points somewhere most people do not expect. Its heading reads “CHECK IF PROPERTY IS SUBJECT TO LEASE(S) OR OCCUPANCY AFTER CLOSING,” and the text addresses property occupied by third parties beyond closing, which is the machinery for a sale with a tenant already in the house.
The rider the contract sends you to
For the seller’s own stay, the contract gives a one-line instruction at the end of paragraph 6(b): “If Property is intended to be occupied by Seller after Closing, see Rider U POST-CLOSING OCCUPANCY BY SELLER.” The addenda checklist in paragraph 19 confirms the pairing, listing T as Pre-Closing Occupancy and U as Post-Closing Occupancy. The form library holds one rider for a buyer moving in early and a separate rider for a seller staying late.
Checking a box on that list is where the job starts. The length of the stay, the charge, what secures it, and the condition the house is handed over in are terms somebody has to write, so have a Florida real estate attorney draft or review the document that carries them.
One claim circulating about these arrangements deserves correcting, because sellers plan around it: the idea that a post-closing stay crosses into Florida’s Residential Landlord and Tenant Act once it runs past 60 days. Section 83.42 is where the exclusions from that part of chapter 83 live, and it lists five, none being a seller’s stay after closing and none turning on a 60-day threshold. The exclusion that does mention a contract of sale, s. 83.42(2), describes occupancy where the buyer “has paid at least 12 months’ rent” or “at least 1 month’s rent and a deposit of at least 5 percent of the purchase price of the property.” That provision covers a buyer who moved in early, which is the Rider T situation.
Your buyer’s mortgage carries the real 60-day clock
There is a 60-day rule in a financed Florida sale, and it sits in the buyer’s loan documents. The Fannie Mae and Freddie Mac uniform security instrument for Florida, Form 3010 (07/2021), states at Section 6, headed Occupancy: “Borrower must occupy, establish, and use the Property as Borrower’s principal residence within 60 days after the execution of this Security Instrument and must continue to occupy the Property as Borrower’s principal residence for at least one year after the date of occupancy, unless Lender otherwise agrees in writing, which consent will not be unreasonably withheld, or unless extenuating circumstances exist that are beyond Borrower’s control.”
Read who that binds. The covenant belongs to the borrower, so the exposure for breaking it is your buyer’s, and the seller’s stay is what makes it impossible to keep. A 60-day post-closing occupancy consumes the entire window, while a two-week stay leaves 46 days of margin. The provision names its own escape, the lender agreeing otherwise in writing, and that consent is worth collecting before anyone signs a rider.
Section 5(a) of the same instrument requires the borrower to keep the improvements on the property insured against the hazards the lender requires. That coverage is directed at the improvements. A seller whose furniture is still in the house after closing is no longer insuring a home they own, which is a gap the written agreement should close.
A cash buyer has no such covenant and no lender consent to collect, which is why the same request draws an easy yes from one buyer and a flat no from another.
What the arrangement becomes once title transfers
At closing the ownership flips, and the labels in chapter 83 follow the ownership. Section 83.43(9) defines a landlord as “the owner or lessor of a dwelling unit,” s. 83.43(17) defines a tenant as “any person entitled to occupy a dwelling unit under a rental agreement,” and s. 83.43(13) defines a rental agreement as “any written agreement, including amendments or addenda, or oral agreement for a duration of less than 1 year, providing for use and occupancy of premises.” A seller paying the new owner for two more weeks in the house fits all three, and the document’s title does not change that.
The consequences run in both directions. If the seller stays past the end date, s. 83.58 lets the new owner recover possession under s. 83.59 and “also recover double the amount of rent due on the dwelling unit, or any part thereof, for the period during which the tenant refuses to surrender possession.” Recovering possession means filing in the county court where the premises sit, with the landlord entitled to the summary procedure in s. 51.011 and the court directed to advance the cause.
Pointed the other way, s. 83.67 forecloses the shortcuts. A landlord may not cause the termination or interruption of utility service, may not prevent the tenant’s reasonable access by changing the locks or using a bootlock, and may not remove the tenant’s personal property except after surrender, abandonment, the statute’s death provision or a lawful eviction. A landlord who violates the section “shall be liable to the tenant for actual and consequential damages or 3 months’ rent, whichever is greater, and costs, including attorney’s fees.”
Both exposures are worth sizing before the stay is agreed. Using $3,000 a month purely to show the arithmetic, two conventions for a daily rate are in common use and they disagree: divided by 30 it is $100.00 a day, while multiplied by 12 and divided by 365 it is $98.63, a gap of $19.18 across a fourteen-day stay. Twelve days of holdover at $100.00 a day is $1,200.00 of rent, and s. 83.58 reaches double that, $2,400.00. Three months at the same assumed figure, the floor for a s. 83.67 violation, is $9,000.00 before costs and fees.
Terms to settle before anyone signs
- Set an end date as a calendar date, and state what happens on the following day.
- Write the daily rate, the convention behind it, and what the deposit secures, so nobody argues between $100.00 and $98.63 later.
- Assign utilities and yard care by name and by date, including who holds the accounts during the stay.
- Fix the condition the house is handed over in, and schedule the walkthrough that confirms it before any held funds are released.
- Record who insures the structure and who insures the belongings inside it, since Form 3010 Section 5(a) answers only the first question.
- Get the lender’s written consent if the buyer is financing a primary residence, and keep it with the rider.
Frequently asked questions
How long can a seller stay in the house after closing in Florida?
No Florida statute sets a maximum. The limits that bind come from the agreement the parties sign and, when the buyer is financing a primary residence, from Form 3010 Section 6, which requires the borrower to occupy the property as a principal residence within 60 days after the security instrument is executed and to keep occupying it for at least a year. A stay using the full 60 days leaves the buyer no margin for a delayed move, so the practical ceiling is set by the lender’s written consent rather than by the covenant’s outer limit.
Can the buyer change the locks if I have not moved out on time?
Not where the arrangement is a tenancy governed by part II of chapter 83. Section 83.67(2) bars a landlord from preventing the tenant’s reasonable access by changing the locks or using a bootlock, and s. 83.67(5) bars removing the tenant’s personal property except after surrender, abandonment, the death provision or a lawful eviction. The penalty in s. 83.67(6) is actual and consequential damages or three months’ rent, whichever is greater, plus costs and attorney’s fees. The lawful route is the possession action under s. 83.59.
Is a post-closing occupancy agreement the same thing as a lease?
What it is called is not what decides. Section 83.43(13) defines a rental agreement to include “any written agreement, including amendments or addenda, or oral agreement for a duration of less than 1 year, providing for use and occupancy of premises,” a description a short post-closing document can satisfy regardless of its heading. The contract groups the two together as well, since paragraph 6(b) speaks of “lease(s) or any occupancy agreements” in one breath.
Where to go from here
A post-closing stay usually exists because two closings did not line up, so the pieces that move those dates are worth checking: which loan changes push a closing back by three days covers the most common cause, and what you actually net at closing shows where an occupancy charge sits against everything else leaving the settlement statement. The obligations that come with any Florida sale are set out in what sellers must disclose on an AS IS sale.
For a read on where your home stands, start with our home valuation tool. When the timing of your sale and your next purchase has to be handled as one decision, book a strategy session with our Central Florida team at mvphomegroup.com/nelsoncruz. A hand-over date agreed in writing, with the lender’s consent attached, costs a few days of planning. The same date left to goodwill is what turns a closed sale into a possession action.
Nelson Cruz, P.A.
Founder & CEO
MVP Home Group, Real Broker LLC
Nelson brings nearly two decades in law enforcement to his work in real estate. View Nelson’s profile or contact our team at 407-901-9939 or [email protected].
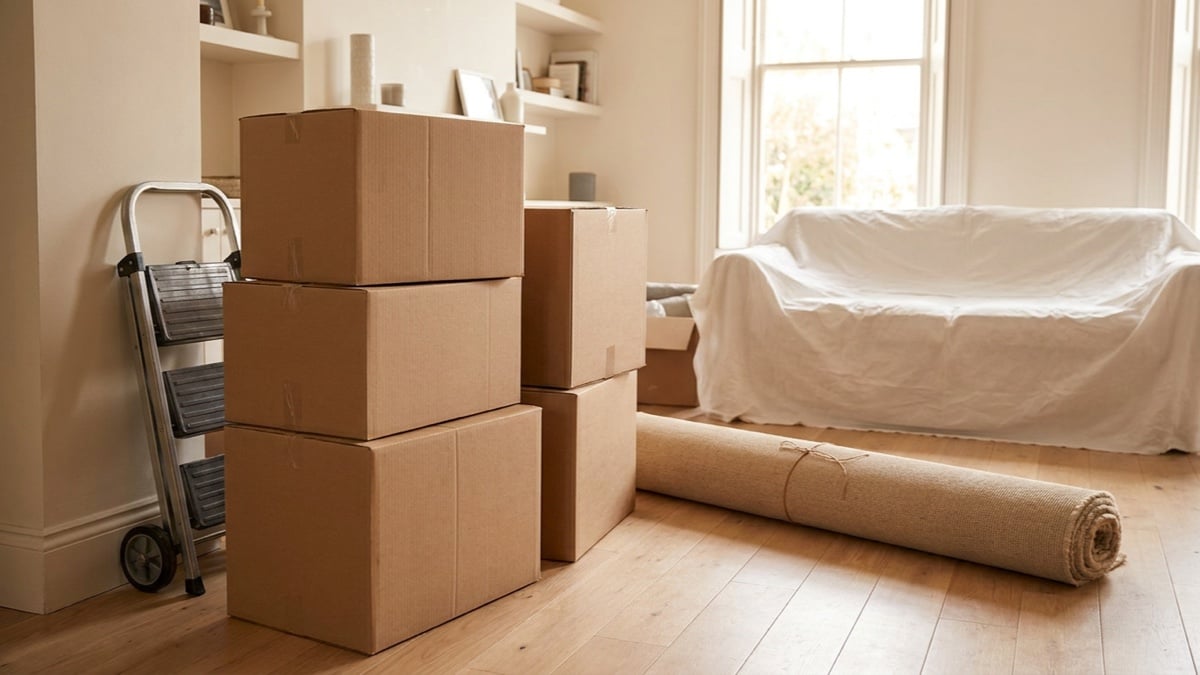
Featured image: AI-generated editorial illustration of a living room partway through a move, with sealed cardboard moving boxes stacked in the foreground, a hand truck standing against the wall, a rolled rug on bare wood floor and a sofa under a dust sheet. Not a particular property or transaction.