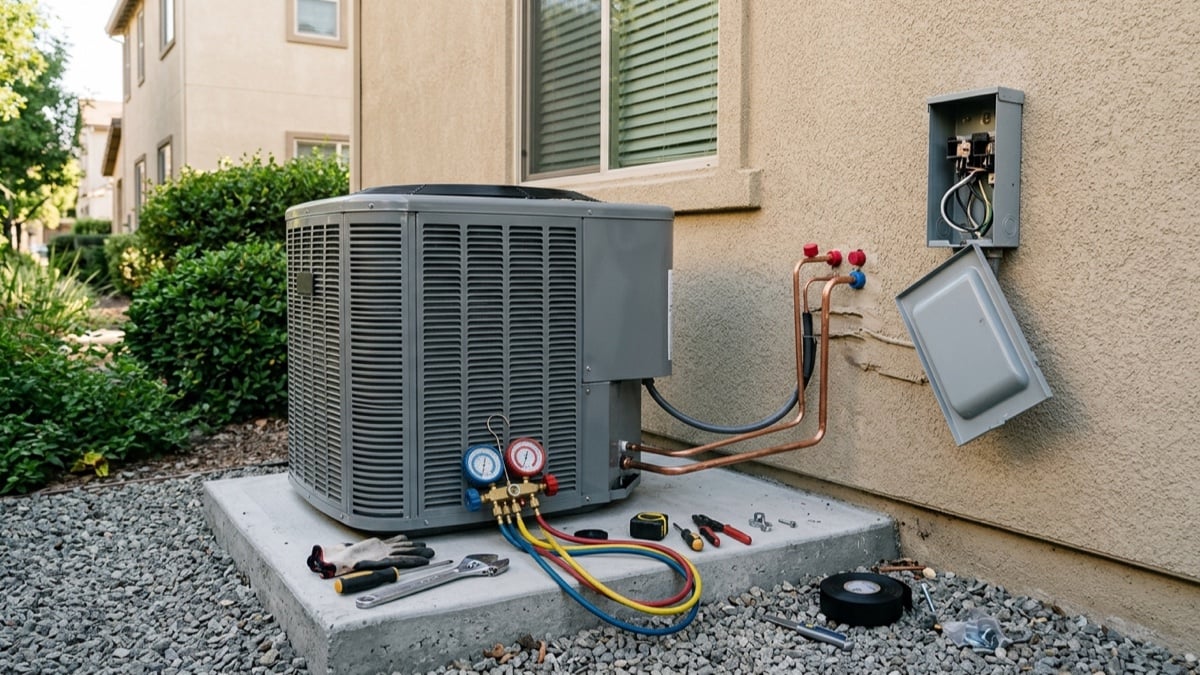
When the repairs a seller agreed to are still unfinished on closing day, the decision about holding money back belongs to your lender rather than to your purchase contract. Conventional and FHA loans both permit funds to be escrowed for incomplete work, and both set conditions narrow enough that many ordinary resale repairs fail to qualify. A price reduction or a correctly worded closing cost credit often reaches the table faster.
That surprises people, because a holdback sounds like something the buyer and seller can simply agree to. Once a mortgage is involved, the escrow has to be one the lender will accept, document and later close out.
Why the lender controls the answer
On conventional financing, Fannie Mae’s rule starts from the default position that improvements, alterations, and repairs on the subject property must be complete when the loan is sold to Fannie Mae. The exception is written for postponed items, and it carries three conditions. The item has to be part of the sales contract, with third party contracts not permitted. It has to be postponed for a valid reason, which the guide illustrates as inclement weather or a shortage of building materials. It also must not affect the ability to obtain an occupancy permit.
Those conditions matter more than the dollar mechanics. A roof a seller promised to replace after a failed inspection is rarely delayed by weather, and rarely written into the sales contract as a postponed improvement.
What a conventional completion escrow actually requires
When an item does qualify, the lender establishes a completion escrow by withholding from the purchase proceeds funds equal to 120 percent of the estimated cost of completing the improvements. If the contractor offers a guaranteed fixed price contract, the escrow only needs to equal the full contract price. On a $9,500 air conditioning replacement, the 120 percent version reserves $11,400.
The work then has to be completed within 180 days of the note date, and the postponed items must not represent more than 10 percent of the “as completed” appraised value, which on a $400,000 appraisal is $40,000. The qualifying conditions bite long before that ceiling does. Completion is proven with the Appraisal Update and/or Completion Report, Fannie Mae Form 1004D and Freddie Mac Form 442.
FHA runs a parallel track. HUD’s handbook tells the lender that if repairs for existing construction cannot be completed prior to closing, it may establish an escrow account under the Repair Completion Escrow Requirements, and that it may do so only “provided the housing is habitable and safe for occupancy at the time of loan closing.” Borrower labor may not be included in the escrow. The lender executes form HUD-92300, Mortgagee’s Assurance of Completion, to set the escrow up, certifies the finished work on form HUD-92051, Compliance Inspection Report, and completes an escrow closeout in FHA Connection within 30 days of closing the account.
Four ways to handle an unfinished repair
| Option | Who has to approve it | The limit that decides it |
|---|---|---|
| Completion escrow, also called a holdback | Your lender | Conventional: 120 percent of the estimate, finished within 180 days of the note date, item must be in the sales contract and postponed for a valid reason |
| Closing cost credit from the seller | Your lender, within contribution caps | Conventional 3, 6 or 9 percent of the price by loan to value; FHA 6 percent of the sales price. Applies to closing costs and prepaids only |
| Repair allowance | Treated as an inducement to purchase on FHA | Reduces the value the loan is calculated on, dollar for dollar |
| Price reduction | Seller, and a new appraisal is not required | No cap. Lowers the loan, the cash due and the Florida deed tax |
| Move the closing date | Both parties, plus the lender’s rate lock and timing | No cap, and usually the cleanest answer when the work is nearly done |
Dollar limits reflect Fannie Mae and HUD policy current as of the dates cited in each section. Confirm your own loan program with your lender.
The phrase “repair allowance” costs FHA buyers real money
Two addenda can move identical dollars and underwrite completely differently. HUD lists repair allowances among the inducements to purchase, alongside decorating allowances and moving costs, and an inducement produces “a dollar-for-dollar reduction to the purchase price when computing the Adjusted Value of the Property before applying the appropriate Loan-to-Value (LTV) percentage.”
Work it through on a $400,000 FHA purchase at the 96.5 percent maximum. The base loan on a $400,000 adjusted value is $386,000. Label $9,500 as a repair allowance and the adjusted value falls to $390,500, so the base loan falls to $376,832.50. The loan shrank by $9,167.50 to deliver $9,500, leaving a net gain of $332.50 before anyone picks up a wrench.
Write the same $9,500 as a credit toward closing costs and prepaid items instead, and it sits inside FHA’s 6 percent contribution limit, which on this price is $24,000. The adjusted value stays at $400,000, the base loan stays at $386,000, and the credit reduces cash at the table. The words in the addendum, rather than the amount, decide which of those two outcomes you get. Our note on FHA loans and seller required repairs in Florida covers which items an FHA appraiser will flag in the first place.
Credits are capped, and capped to the wrong things
Seller credits feel flexible until you read what they may pay for. Fannie Mae limits interested party contributions to 3 percent of the price above 90 percent loan to value, 6 percent from 75.01 to 90 percent, and 9 percent at 75 percent or below, with investment properties held to 2 percent. On a $400,000 purchase those caps are $12,000, $24,000 and $36,000.
The cap is rarely the problem. The permitted uses are. Contributions may go toward closing costs and prepaid items, and they may not be used for the down payment, to meet reserve requirements, or to meet minimum borrower contribution requirements. A $9,500 credit therefore helps only if you have close to $9,500 in closing costs and prepaids to absorb it, and on the conventional side an excess contribution becomes a sales concession that gets deducted from the sales price, with loan to value then calculated on the lower of the reduced price or the appraised value.
What a price reduction does to your Florida numbers
A price reduction is the plainest instrument available, and it is the only one of the four that reaches the state tax line. Florida’s documentary stamp tax on a deed runs at 70 cents on each $100 of the consideration in every county except Miami-Dade, and the Department of Revenue defines consideration to include the money paid or agreed to be paid.
Cutting a $400,000 price to $390,500 moves the deed tax from $2,800 to $2,733.50, a saving of $66.50 for whoever pays it under your contract. A credit of the same size produces no such saving, because the consideration recited on the deed does not change. The mechanics of who pays which stamp are in our guide to Florida closing taxes and mortgage doc stamps.
The reduction also resizes the loan. At 95 percent loan to value, dropping the price by $9,500 takes the loan from $380,000 to $370,975 and the down payment from $20,000 to $19,525. Your cash at the table falls by $475, and you still owe a contractor $9,500 later. A price cut finances the repair over thirty years. A usable credit hands you the money on closing day. Pick according to which one you are short of.
What to settle before closing day
- Ask your loan officer in writing whether this specific item qualifies for a completion escrow, before the addendum is signed.
- Get a written contractor estimate. A conventional escrow is funded at 120 percent of it.
- Confirm the unfinished work will not hold up a certificate of occupancy, which disqualifies a postponed item outright on conventional financing.
- Run the credit and the reduction against your own closing cost figure before choosing, since a credit you cannot spend is worth nothing.
- Watch the wording. “Repair allowance” and “credit toward closing costs and prepaid items” are underwritten differently on FHA.
- Build in time. Late changes affect your Closing Disclosure schedule, covered in our note on the Closing Disclosure three day rule in Florida.
- Use the walk-through for what it is designed to catch. Our guide to the Florida walk-through and seller obligations explains what you can still raise at that point.
Frequently asked questions
Can the title company just hold the money without telling the lender?
Not on a financed purchase. The escrow has to be one the lender establishes and documents. On FHA the lender executes form HUD-92300 to create it and certifies completion on form HUD-92051, then closes the escrow out in FHA Connection within 30 days. Funds parked under a side agreement sit outside that process.
Will a seller credit pay for my new air conditioner?
No. Interested party contributions are limited to closing costs, prepaid items and discount points on both conventional and FHA loans. Money intended for the repair itself is handled as a repair allowance, which FHA counts as an inducement to purchase that reduces the value your loan is based on.
What proves the repair was finished afterward?
On conventional financing it is the Appraisal Update and/or Completion Report, Fannie Mae Form 1004D or Freddie Mac Form 442. On FHA it is form HUD-92051, Compliance Inspection Report, signed and dated by an approved inspector, with local government inspection accepted alongside the underwriter certification.
Where to go from here
For the condition questions that sit upstream of all of this, see our guide to Florida seller disclosure and as-is contracts.
If you want your own numbers run against a particular property and loan program before your inspection period closes, book a strategy session with our team at mvphomegroup.com/nelsoncruz. This is general information about lender policy and Florida tax law rather than legal or lending advice; your loan program, your contract and the current guides control, and all of them can change.
Nelson Cruz, P.A.
Founder & CEO
MVP Home Group, Real Broker LLC
Nelson brings nearly two decades in law enforcement to his work in real estate. View Nelson’s profile or contact our team at 407-901-9939 or [email protected].